Amex
- 4.8
- Rating
- 10.00M
- Installs
- Free
- Price
 Analysis by App-foxy
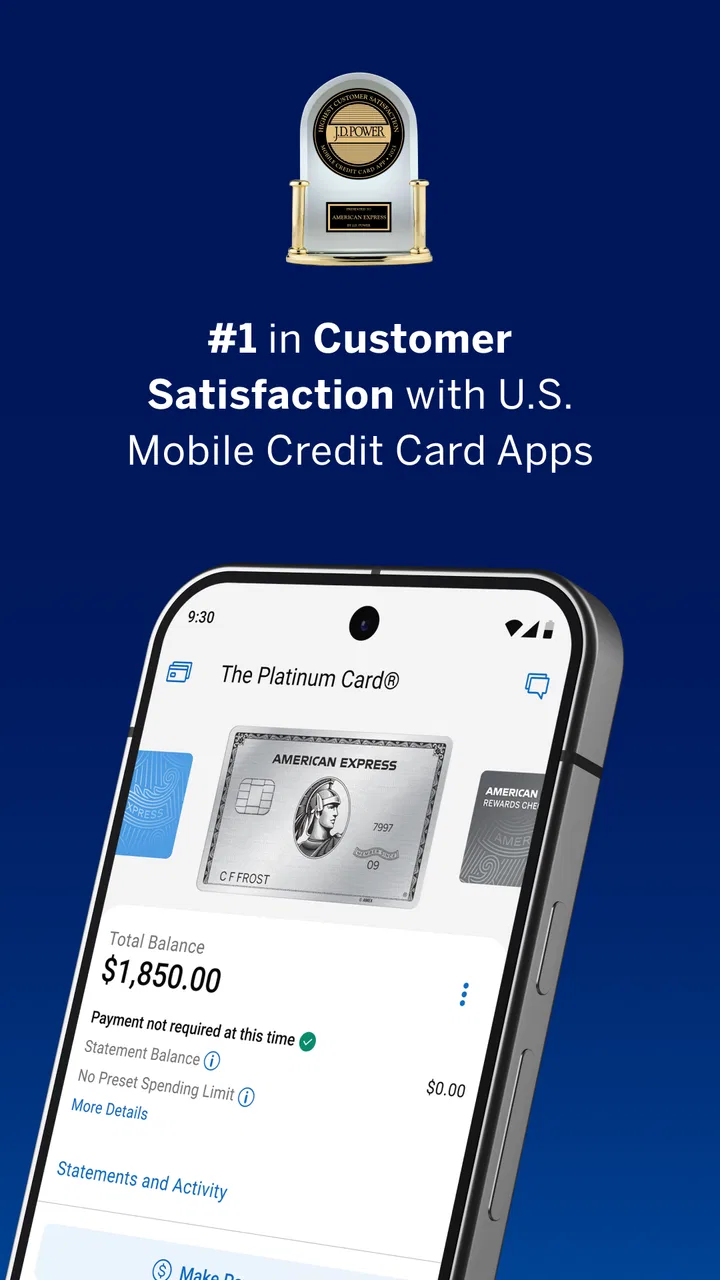
Managing a credit card from a phone sounds simple until you need to do something at an inconvenient moment: check whether a payment went through, confirm available balance before buying something, or use rewards while you are away from a computer. That is the space where Amex makes sense. I tested it as a finance app from American Express, and my overall impression is that it is most useful when you already have an American Express account and want a direct mobile route to the information and actions you use most.
The app is free and available to Everyone, which makes the entry point straightforward. It has been around since Dec 2, 2010, and the current version is 7.27.1 for devices running OS 12 or later. Its 4.5 average from around 47 thousand ratings and more than 10 million installs suggest that it has become a familiar tool for cardholders, although popularity is not a substitute for checking whether its account tools match your own card and habits.
How Amex feels when your connection matters
The central experience is connected account access. When I open the app to view a balance, make a payment, or inspect rewards, I am relying on the phone reaching American Express services and receiving current account information. That is worth keeping in mind because a finance app is not like a notes app or a downloaded game. The value comes from fresh information, so a weak signal can turn a quick check into a wait or an incomplete-looking session.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk
View All News


In a strong connection, the workflow feels naturally suited to short visits. I can open the account, look for the figure I need, and leave without sitting at a desk. That is especially convenient for checking spending before a purchase or reviewing whether a recent payment appears in the account. The app’s purpose is not to replace every financial task, but it does put the most time-sensitive card questions close at hand.
A realistic example is buying something while traveling. Before paying, I might want to confirm that the purchase will fit within my available spending room, then later check the account after the transaction appears. With a reliable connection, the app gives me a more useful view than relying on memory or an old statement. If the network is congested inside a shop or the phone is switching between mobile data and Wi-Fi, I would avoid repeatedly tapping buttons and instead wait for the screen to finish loading before trying again.
The important distinction is that this is a live account tool, not a static wallet. A screen that was accurate earlier may not reflect a newly posted transaction or payment until the app successfully connects again. I treat the latest visible information as useful for decisions, but I still allow for the normal delay that can happen between an action and its appearance in an account.
Payments are convenient, but timing still needs attention
Making a payment from a phone is one of the strongest reasons to use the app. It removes the need to find a desktop browser when a due date is approaching or when I simply want to take care of the bill after reviewing the balance. The convenience is practical rather than flashy: fewer steps between noticing an obligation and acting on it.
That convenience should not encourage last-second habits. A payment action may require a dependable connection, account authentication, and enough time for the result to become clear. If I submit something while moving between networks, I would first check whether the app shows a confirmation or updated account state before attempting it again. Duplicate actions are an avoidable risk whenever a financial screen appears slow.
The app is also better for people who prefer to monitor an account in small visits rather than perform a large monthly review. I can use a quiet moment to look at the balance, then return later to examine rewards or recent activity. That pattern makes the phone useful as a regular checkpoint, although it does not remove the need for personal budgeting outside the app.
Mobile situations where the app earns its place
The best use cases are mobile by nature. I would choose it when I am away from my computer, when I want to check an account before a purchase, or when I need to handle a payment without opening a full browser session. The compact format also suits quick reward checks, particularly when I am deciding whether an available benefit is relevant to a purchase or whether I should save it for another use.
Travel is a particularly clear example. A cardholder may need to check the account at an airport, in a hotel, or while comparing a purchase in another city. In those moments, the app is more practical than waiting until returning home. The trade-off is that these are also places where connectivity can be inconsistent. I would not make the app my only way to organize a trip; I would keep essential travel details and a backup payment plan available separately.
Another useful routine is a short evening review. After using the card during the day, I can check the account from the phone rather than letting several purchases accumulate unnoticed. This is not a complete spending analysis, but it can help catch a transaction that deserves attention while the context is still fresh. The benefit comes from frequency: small checks can be easier to maintain than a larger review that I keep postponing.
People who manage several financial products may also appreciate having the American Express account in its own dedicated environment. At the same time, someone who wants one dashboard for bank accounts, cards, investments, and household budgets may prefer a broader personal-finance service. Those alternatives can be better for an overall financial picture, while this app is more focused on direct American Express account access.
What happens when loading fails
Connectivity problems are more frustrating in a finance app because the user is usually trying to confirm something important. A blank or delayed balance can create uncertainty, especially if I have just made a payment or am standing at a checkout. My practical approach is to stop after one attempt, check whether the phone has a stable connection, and reopen the relevant screen rather than repeatedly submitting the same action.
If the app does not immediately reflect a payment or transaction, I would not assume that the action failed solely because the display is slow. I would look for a clear status, allow time for the account to update, and avoid creating a second payment until the first attempt is understood. This is a general financial safety habit, but the app’s mobile design makes it especially important because a user may be acting quickly on a small screen.
The recovery experience also depends on authentication. Account access is intentionally more serious than opening a casual utility, so a login or security check can feel like friction when I am in a hurry. I consider that a reasonable trade-off for financial access, but it means the app is not ideal for someone who expects every task to open instantly without verification.
When the network is unreliable, a browser session on a computer may be the better alternative if I need a larger view or a more deliberate review. The app wins for immediacy and portability; the browser can feel easier when I need to compare multiple pieces of account information or carefully document what happened. Neither option eliminates the need to verify the final state after an important action.
Using data carefully without losing the main benefit
The app’s connected nature means that mobile data can become part of the experience, particularly for people who are often away from Wi-Fi. I would use it for focused account checks rather than leaving it open while doing unrelated tasks. Short sessions are enough for most of its main purposes: check the balance, review the relevant account area, make a considered payment, or inspect rewards.
That approach has two advantages. It keeps the experience efficient, and it reduces the chance that I will make a rushed decision while a screen is still updating. I also prefer to use a stable, trusted connection for sensitive account activity whenever one is available. Public networks may be convenient, but a financial session deserves the same caution I would apply to any important account.
Data-conscious use is not only about consumption. It is also about avoiding unnecessary refreshes. If I am checking whether a transaction has posted, refreshing every few seconds is unlikely to make the result arrive sooner and may make the session more confusing. A better workflow is to check once, note what the app clearly reports, and return later if the account needs time to update.
Rewards are another area where a deliberate approach helps. I would not open the rewards section merely to browse endlessly on a weak connection. Instead, I would decide what I am trying to confirm before opening it: whether a reward is available, whether it suits a planned use, or whether I need to review the account after a redemption. This turns a potentially scattered mobile session into a specific task.
Who will benefit most from Amex?
I would recommend it first to existing American Express cardholders who want direct access to their account from a phone. It is a good fit for people who make payments away from a computer, check balances before spending, and prefer frequent small reviews. The free price also makes it an easy companion to an existing account rather than an extra paid service.
It is less compelling for someone who does not use American Express or who wants a complete household-finance dashboard across many providers. It is also not the right answer for a person who needs a financial tool to function independently of a network connection. Because the important information is account-based and current, connectivity is part of the practical requirement even when the app itself is easy to navigate.
I would also be cautious about treating the app as a budgeting system. It can help me observe card activity and make account decisions, but a dedicated budgeting tool may be better for setting categories, tracking cash expenses, or combining finances across a household. The choice depends on whether the priority is managing the American Express relationship or building a broader financial plan.
My verdict after using it on the move
Amex succeeds because it focuses on the moments when a cardholder wants an answer or an action without reaching for a computer. Balance checking, payments, and rewards access are much more useful when they are available during everyday movement, and the app’s long presence and strong user adoption show why this format has lasting appeal. The experience is direct, familiar, and free to use for the people it is designed for.
Its main limitation is inseparable from its purpose: the app depends on a successful connection and careful confirmation when an action matters. A slow network can make a simple task feel uncertain, and a phone screen is not always the best place for a detailed financial review. I would use it for quick, purposeful account management, then switch to a larger or broader tool when I need deeper planning.
For an American Express customer, I think it is worth installing, especially if mobile access will help you check spending and handle payments before they become chores. My advice is to use it deliberately: open it with a clear task, rely on a stable connection for important actions, and verify the result instead of repeating taps when the network hesitates. That balance lets the app do what it does best without confusing convenience with complete financial management.
FAQs for Amex
01What features does the Amex app offer?
The Amex app provides a comprehensive suite of features for cardholders. Users can manage their accounts, view transactions, pay bills, and track spending. Additionally, it offers rewards management, enabling users to redeem points directly through the app. Security features like biometric login and account alerts add an extra layer of protection.
02Is the Amex app secure to use for online transactions?
Yes, the Amex app prioritizes security with multiple features. It uses encryption to protect your data and offers biometric login options, such as fingerprint or facial recognition. Furthermore, users receive real-time alerts for any suspicious activity, providing peace of mind when managing finances through the app.
03Can I manage multiple accounts with the Amex app?
Absolutely. The Amex app supports the management of multiple accounts. Users can easily switch between different Amex cards, view individual transactions, and manage each account's specific settings. This feature is particularly beneficial for those with personal and business accounts under Amex.
04Does the Amex app offer customer support?
Yes, the Amex app provides robust customer support options. Users can access 24/7 customer service directly through the app, via chat or call. Additionally, the app includes a comprehensive FAQ section and troubleshooting guides to assist with common inquiries and issues.
05Are there any fees associated with using the Amex app?
Using the Amex app itself is free of charge. However, standard transaction fees associated with your specific Amex card may apply. It's important to review your card's terms and conditions for details on any fees related to transactions or specific services offered through the app.
Pros
- User-friendly interface for easy navigation.
- Real-time alerts for transactions and payments.
- Robust security features for safe usage.
- Comprehensive rewards tracking and redemption.
- Seamless integration with financial tools.
Cons
- Limited features for non-cardholders.
- Occasional app crashes reported by users.
- Some features require frequent updates.
- High data usage for real-time notifications.
- Compatibility issues with older devices.

Amex
Gallery